Pay with cards, cash and transfers
Compare the pesos you actually receive, keep independent payment options and know how to document a failed transaction.
By ExpatShield Editorial · Last reviewed
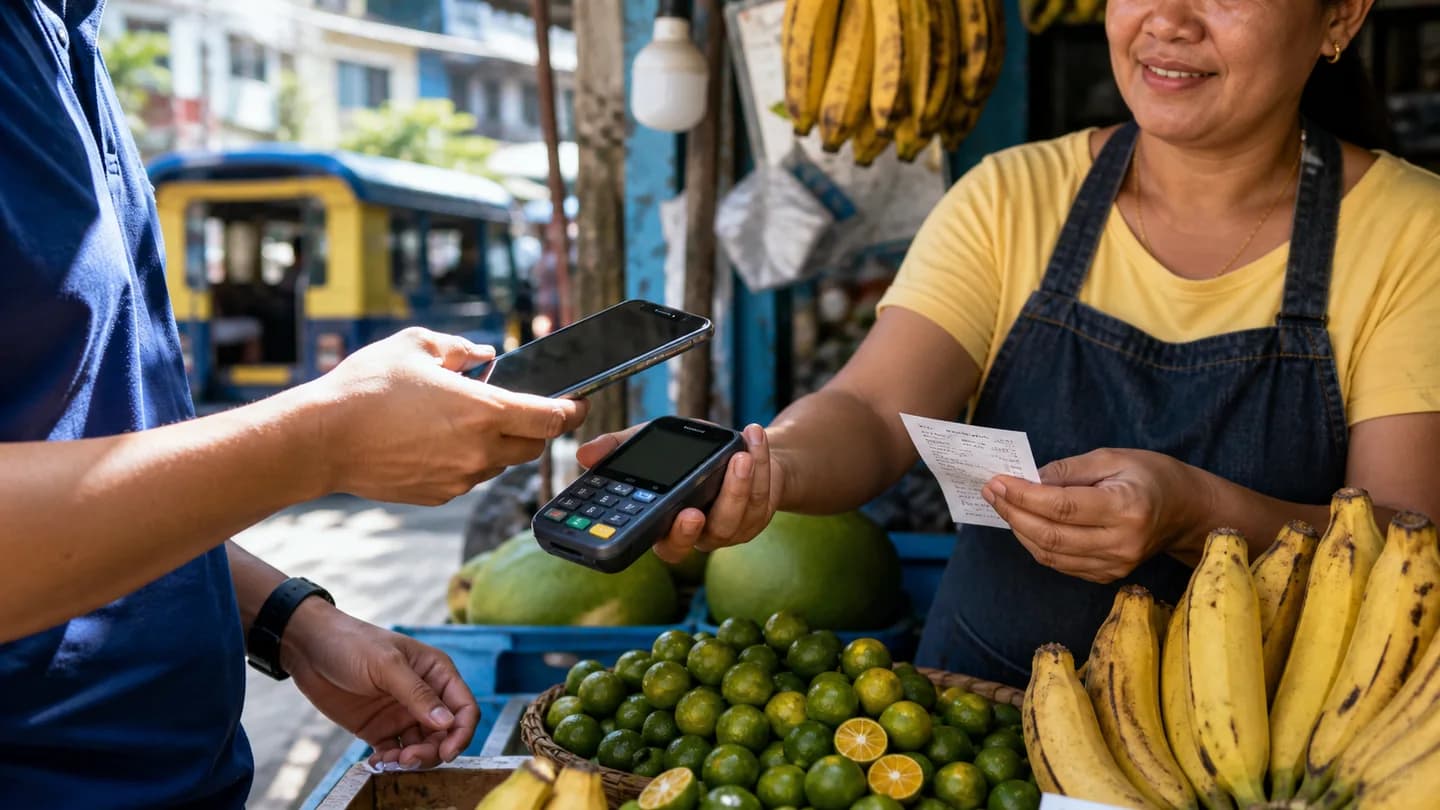
Compare the final amount
A transfer's advertised fee is only one part of the cost. Ask what leaves the sending account and what the recipient can spend after exchange spread, receiving charges and any withdrawal fee. Compare offers at roughly the same time and for the same sending amount, currency and delivery method. Keep promotional first-transfer rates separate from the costs you would pay every month.
Consider this invented example. Provider A converts 1,000 units of a foreign currency at PHP 50 after deducting a 10-unit fee: 990 times 50 equals PHP 49,500. Provider B charges no sending fee but converts at PHP 49: the payout is PHP 49,000. Provider A delivers PHP 500 more before any receiving or withdrawal charges. These are arithmetic assumptions, not quotes from real providers.
Choose the method for the task
| Method | Check before relying on it |
|---|---|
| Card | Issuer fees, limits, merchant acceptance and recovery contact |
| Cash withdrawal | Operator fee, issuer fee, available limits and safe access |
| Bank transfer | Recipient name, account details, net payout and expected delivery |
| E-wallet | Your eligibility, registration, limits, cash-out costs and recovery process |
BSP financial resources offer a route to provider and consumer information. Registration or regulation is a starting check, not a guarantee that a transaction will be instant or that every foreign visitor can use every product. Ask the provider about your status and the account's conditions before loading significant funds.
Build a practical backup
Carry enough accessible cash for your immediate route and household needs without making one wallet your entire reserve. Keep two independent payment methods where possible, with contact details available if your usual phone is lost. Two apps tied to the same blocked account or missing SIM may fail together.
When a terminal or ATM offers a conversion, read the exchange rate and total before accepting. Compare those terms with your issuer's disclosed conversion charges; there is no need to choose in a hurry. Shield the PIN entry and cancel if the machine or payment request seems wrong. Never let a stranger guide you through sharing an OTP.
Resolve a payment that did not arrive
- Check the transaction status in the provider's official app or site.
- Compare the recipient details with the intended destination privately.
- Save the reference, amount, time and displayed error.
- Contact the provider through an independently opened official channel.
- Avoid sending again until you understand whether the first payment is pending or failed.
Keep dispute records factual and ask for a case reference and next step. This is financial information only; provider terms determine the actual charges and process for your transaction.
Read next
Open and manage a Philippine bank account · Avoid common travel and payment scams.
Use the BSP rate comparison steps to compare final peso payouts on the same basis. Bring the actual quotes and fees to a consultation if you need help organizing a payment-access plan.
Sources and direct attribution
- BSP financial products and services accessed September 5, 2026
- BSP reference exchange rates accessed September 5, 2026